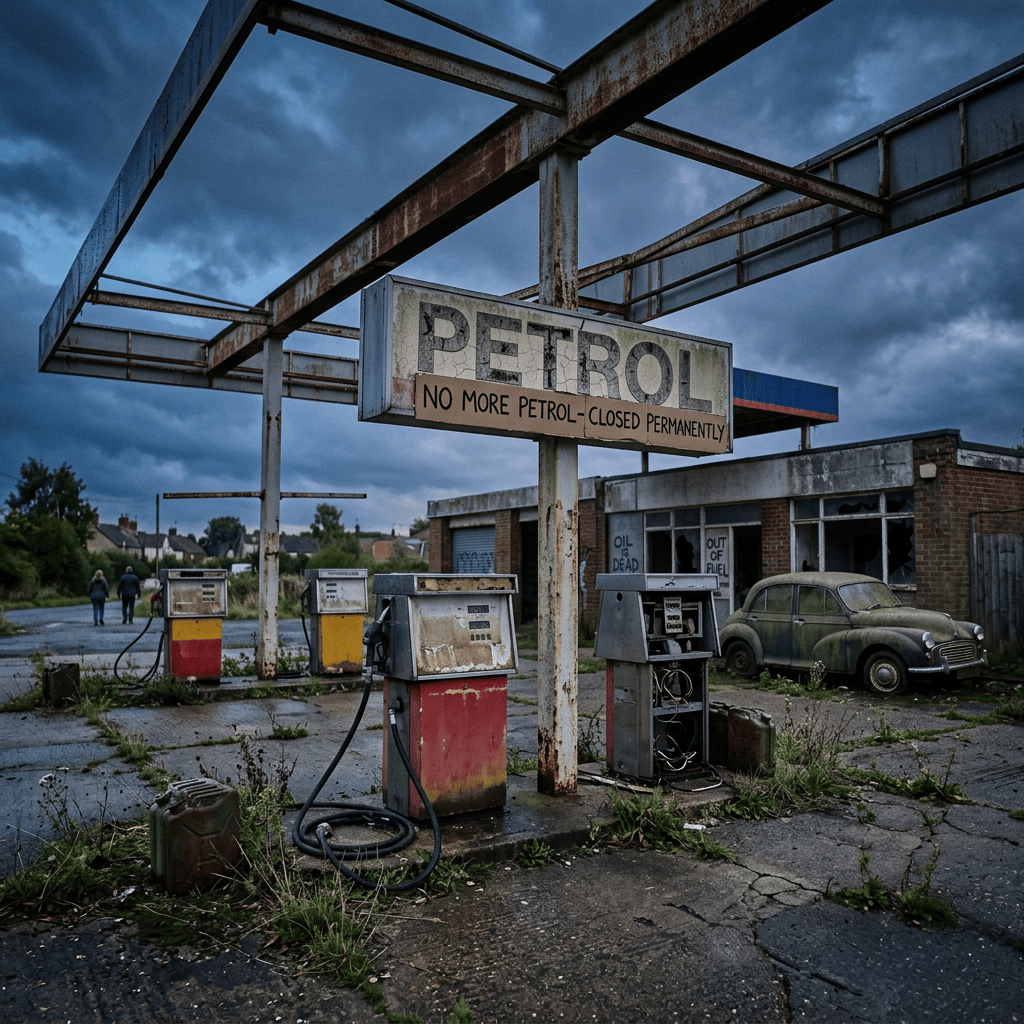
Oil has been part of human life since ancient times, but its importance began to accelerate from the 1700s onward. In 1859, Edwin Drake drilled the first modern oil well in Pennsylvania, marking the beginning of the modern petroleum industry. After emerging toward the end of the Second Industrial Revolution, oil became a powerful force that eventually spread across the entire world.
Although continuous technological advances are gradually overshadowing oil’s global influence, oil is still far ahead. Electricity, the technology that could eventually dethrone the oil industry, remains well behind oil for now.
But the question is:
Is the oil era really coming to an end?
When evaluating the future development of electric vehicles, rather than assuming a fixed growth rate, it may be more realistic to use the growth rate electric vehicles have demonstrated so far as a starting point.
According to IEA data, electric vehicles accounted for approximately 2% of global new car sales in 2018, 4% in 2020, around 9% in 2021, 18% in 2023, more than 20% in 2024, and approximately 25% in 2025.
In other words, the share of electric vehicles in new car sales increased approximately 12.5-fold between 2018 and 2025. This corresponds to an annual compound growth rate of approximately 43%.
However, this rate cannot continue indefinitely. As the market share of electric vehicles approaches 100%, their growth rate will naturally begin to slow. Therefore, rather than relying on a single forecast, it is more reasonable to consider several different scenarios for the future.
In the fast scenario, a significant portion of the high growth rate seen so far is maintained. The share of electric vehicles in new car sales could reach 50-60% by 2030 and 80-90% by 2035. Assuming that vehicles are replaced on average every 15 years, electric vehicles could reach approximately 50% of the total global vehicle fleet around 2045.
In the moderate scenario, the growth rate slows significantly over time. The share of electric vehicles in new car sales could reach approximately 40-45% by 2030, 60-70% by 2035, and around 80% by 2040. In this case, electric vehicles could reach 50% of the total global vehicle fleet around 2050.
In the slow scenario, the expansion of electric vehicles slows more noticeably. Their share of new vehicle sales could remain around 35-40% by 2030 and 60-70% by 2040. In this case, electric and petroleum/internal-combustion vehicles could reach a 50/50 balance in the global vehicle fleet around 2055-2060.
Among these three scenarios, when we consider both the growth rate electric vehicles have demonstrated so far and the natural slowdown that may occur over time, the period around 2048-2052 appears to be a more reasonable moderate scenario.
Therefore, if current trends continue, it is possible that around 2050 electric vehicles and petroleum/internal-combustion vehicles will become numerically comparable within the global automobile fleet.
However, from the perspective of oil, the critical period will not be 2050, but rather 2030-2040. As an increasingly large share of new vehicle sales shifts toward electric vehicles, the growth of oil demand may begin to come under pressure much earlier, even while the existing vehicle fleet remains largely dependent on petroleum.
For this reason, the rise of electric vehicles should not be viewed as a transformation that will eliminate oil overnight. Instead, it should be seen as a long-term transformation that first slows the growth of oil demand and then gradually pushes oil demand downward as the existing petroleum-powered vehicle fleet ages and is replaced.
Moreover, the transition away from oil will probably take much longer for ships, one of the largest components of the transportation sector, than it will for automobiles. Therefore, it may not be possible for everyone reading this article to witness the period when oil completely disappears.
However, we may witness the period when oil’s power begins to weaken and the oil economy starts moving forward at a much slower pace.
One of the most important indicators of this transformation will be the behavior of international capital. If major global capital groups stop expanding their investments in oil exploration, production, distribution and refining companies and begin redirecting their investments toward other sectors, this could become one of the most important indicators that the oil era is entering a new phase.
The United States, which has played a central role in controlling and protecting the global oil system, may also enter a period in which it increasingly exercises its power through different areas. If this transformation coincides with the middle of this century, it could also mark the beginning of a new era in global politics.
Perhaps the years when oil begins to lose its importance will also coincide with a period of political and economic turbulence preceding a major global transformation.
Oil did not, by itself, cause the great world wars. However, it became one of the most important elements of global power struggles throughout the last century.
So how will oil be priced as we approach its final years?
In my experience with financial markets, an asset, company, or financial instrument does not necessarily disappear quickly as it approaches the end of its dominant period. On the contrary, it can sometimes experience a powerful final phase of appreciation and momentum.
No financial asset willingly sacrifices itself in nominal terms. An asset may make one final attempt to attract investors with high valuations and reach another major peak.
For this reason, during the final stages of the oil era, we may see the ownership stakes of major shareholders in oil-related companies decline while the proportion of publicly traded shares increases. Oil prices driven higher by potential energy crises could push company valuations upward and accelerate the movement of capital toward sectors that are likely to shine in the post-oil era.
Of course, this process will not happen overnight.
However, based on the calculations and the moderate scenario outlined above, by the 2050s, oil’s current central position in the global economy may have changed dramatically.
This leads to another question:
When will oil experience its final major rally?
Developments around the Strait of Hormuz, tensions between Iran and the United States, and similar geopolitical risks are among the factors that could once again push oil prices toward major peaks.
Oil reached approximately $146 per barrel before the 2008 global financial crisis. It is not impossible that oil could attract a new generation of investors at even higher prices in the future.
And this is where a “Petromania” could emerge.
Not because oil will rise forever, but because it could experience its final major pricing wave as it approaches the end of its dominant era.
Perhaps this will be the greatest irony of the oil age:
Just as oil begins to lose its power, its price and investor interest could reach one final peak.
The oil era will not end in a single day.
First, its power will decline. Then its influence will diminish. Eventually, the global economy will begin adapting to a system that relies less on oil.
Perhaps we will never see the day when oil completely disappears.
But we may very well witness the final great chapter of the oil era.
Thank you for reading my article.
Serdar AYDOĞAN


Yorum bırakın